Gamma Exposure Explained: From Options to Hedge Pressure
Understand GEX units, dealer positioning assumptions, and a practical method for turning gamma exposure into conditional trading scenarios.
By OrderMap Research4 min read
On this page
What GEX actually measures
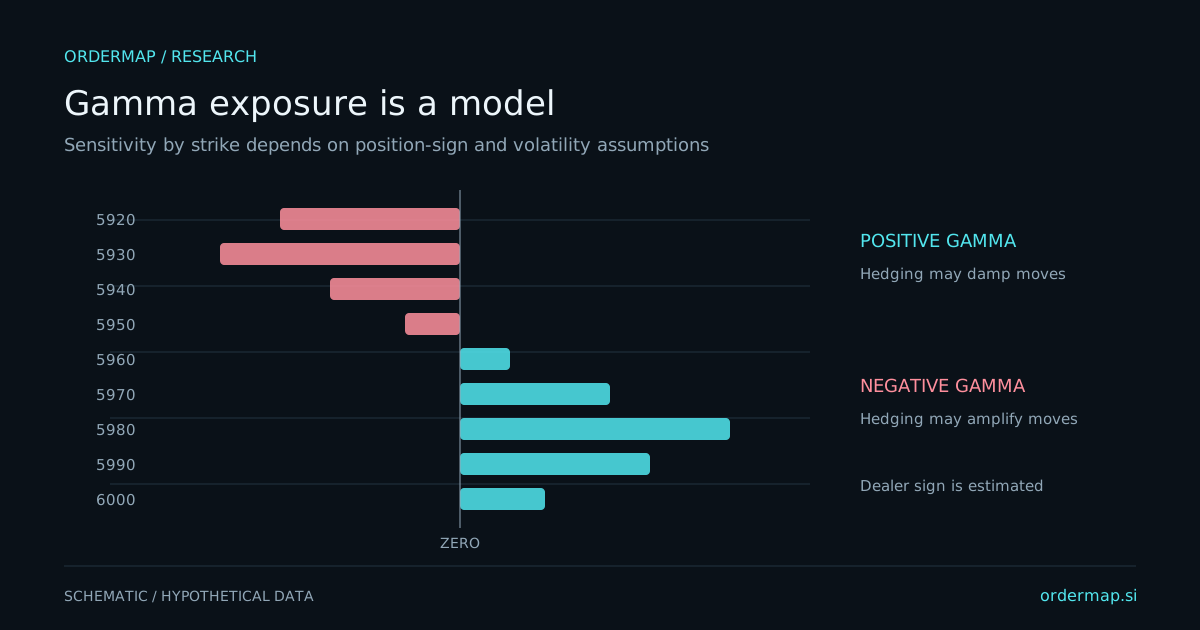
Gamma exposure connects an options portfolio to a question about its hedge: how much could its delta change when the underlying price moves? Gamma measures the change in delta per unit move. GEX scales that sensitivity by contract size and position quantity. It is a sensitivity estimate, rather than a record of futures that somebody has already bought.
For a long vanilla call or put, gamma is generally positive. A short position reverses that sign. A dealer portfolio combines many positions, so a positive number for one strike can coexist with negative gamma across the whole book. The sign of a put's delta must not be confused with the sign of its gamma. The Options Industry Council's gamma guide explains the sensitivity and its relationship to moneyness and expiration.
Start with the units
Suppose a hypothetical equity option has gamma of 0.02 per dollar, a 100-share multiplier, and a modeled dealer position of 1,000 long contracts. A one-dollar increase changes the portfolio's delta by approximately 2,000 shares: 0.02 times 100 times 1,000. Keeping a locally neutral hedge would require selling roughly 2,000 shares, before other risks and transactions are considered.
That result is shares per dollar move. To express dollar hedge sensitivity for a one-percent underlying move, a common convention multiplies signed gamma times quantity times multiplier times spot squared times 0.01. At a hypothetical spot of $100, the result is $200,000 per one-percent move. Other dashboards use different scaling. A dramatic number is meaningless until its unit and convention are clear.
| Label on a dashboard | Question it should answer | What to verify |
|---|---|---|
| Contract gamma | How quickly does one contract's delta change? | Multiplier already included or excluded |
| Share gamma | How many shares of delta change per dollar? | Position sign and underlying units |
| Dollar GEX per 1% | What dollar hedge change accompanies a 1% move? |